If you are thinking about moving, the question is fairly simple: would it be better to do it now, or wait until next year?
The answer matters. You might be selling a flat to buy a house, moving out of London, or deciding whether the home you have been watching is finally within reach.
Mark’s view: I think 2027 will be a tough market for sellers, with further pressure on prices where buyers have plenty of alternatives. But I also think a move is a life decision. If you can afford it, and it gives you the home and life you want, uncertainty about next year’s prices needn’t stop you.
London is already moving differently
The latest HM Land Registry and ONS figures, released on 18 November, put UK house prices 1.2% higher than a year earlier. London was down 3.5%.
Within the capital, flats were down 6.3% annually. Terraced houses were down 1.2%, while semi-detached houses were up 0.5%. Those are September 2026 figures based on completed transactions; recent estimates can be revised.
For me, the gap matters more than the headline. Someone selling a flat and buying a family house may find that the two ends of their move behave quite differently. A general recovery elsewhere in the country does very little for them if their own buyer is struggling with the monthly cost.
Even the forecasters disagree
Savills’ November forecast puts mainstream London prices down 3.5% in 2027, with growth returning in 2028. Its forecast concerns the second-hand market, where mortgage affordability does much of the work.
Connells Group takes a more positive view: it expects London prices to be 2% higher year on year in the final quarter of 2027, helped by an easing in mortgage costs.
These are different models, with different assumptions. They are not a reliable upper and lower limit for your home.
I would pay attention to what sits underneath them. A recovery needs buyers to feel more comfortable about both their repayments and their financial position. If that improvement takes longer, sellers will have to work with the budgets buyers actually have.
The monthly payment still matters
On 5 November, the Bank of England raised Bank Rate to 4%. It is too easy to talk about next year as though cheaper borrowing is already agreed.
Fixed mortgage rates also reflect funding costs and expectations about future rates. They do not simply follow each Bank Rate decision. For anyone planning a purchase, the mortgage available to you matters much more than a confident prediction about where rates might eventually settle.
There is also more competition for buyers’ attention. Rightmove’s November report says the number of homes for sale across Great Britain is at its highest in 12 years. Its index measures asking prices, so it should be read separately from completed-sale figures.
My reading is that sellers need to give someone a convincing reason to choose their home. An ambitious price needs evidence behind it.
Your home will have its own competition
A London average cannot tell you how someone will react when they walk through your front door.
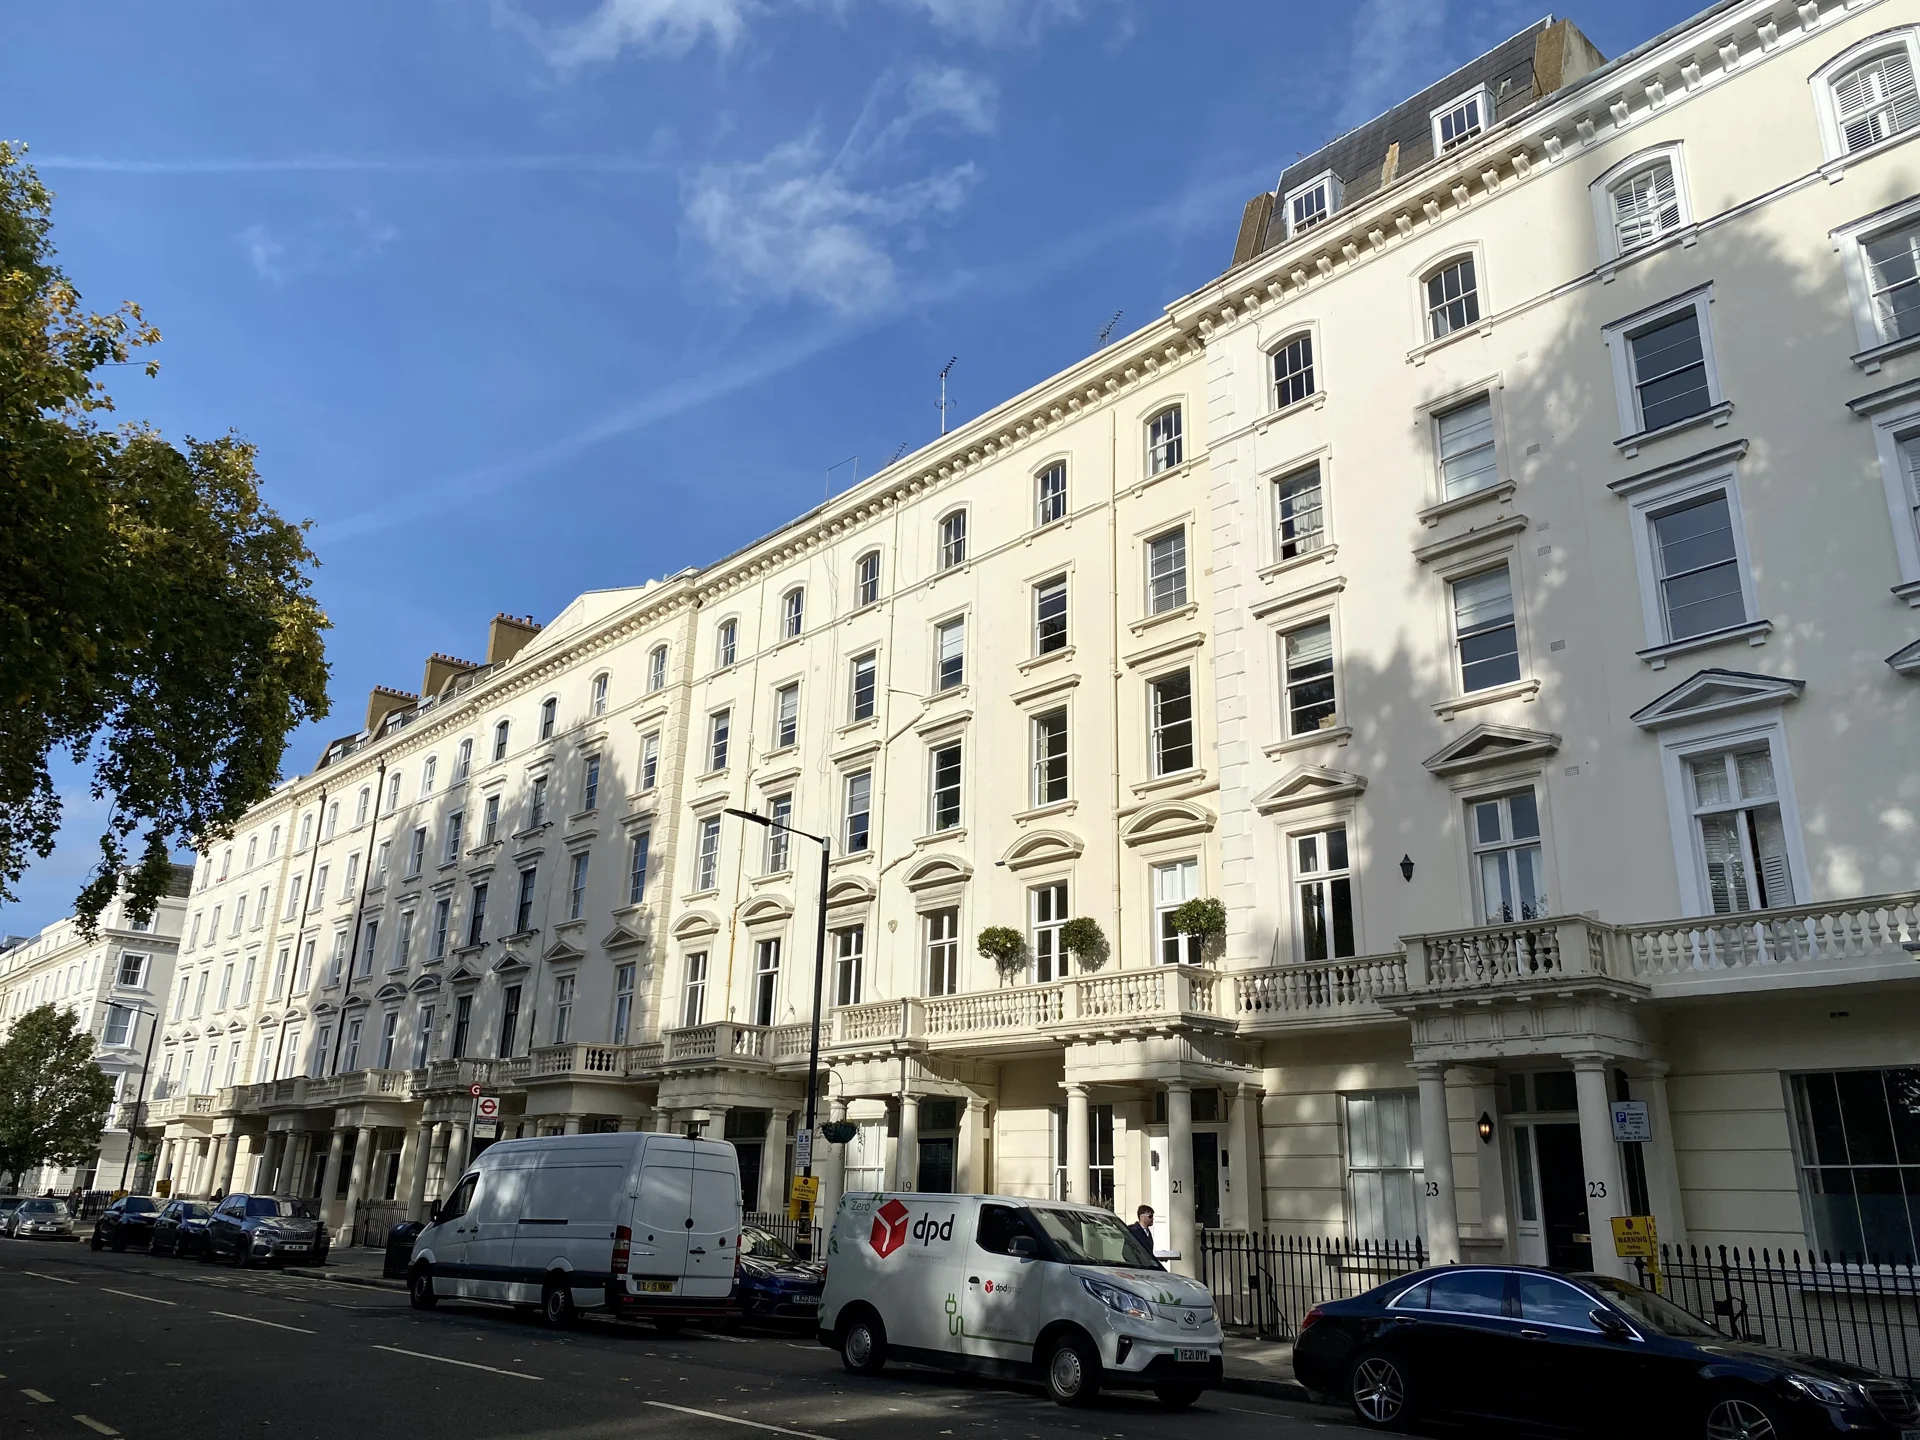
In Chelsea or Pimlico, I would want to understand the light, floor, layout, lease, service charge and any proposed works before discussing the price of a flat. A lovely room can create an emotional connection; the building’s paperwork can still change the decision.
For a family house in Clapham or Fulham, the conversation might centre on the garden, usable living space, school journey and how much work lies ahead. The right comparisons are the homes that the same buyer could realistically choose.
That is where I would concentrate the effort in 2027: identifying the likely buyer, understanding their alternatives and presenting the home so its strengths are immediately clear.
If you are selling, price the whole move
Waiting can make sense when you have the time and a sound reason. I would be more careful about waiting purely because a forecast promises a better market.
If you are buying as well, look at both transactions together. A lower sale price can sometimes be offset by a better purchase price. Equally, selling a flat in a weaker segment and buying a house in a firmer one can make the gap harder to bridge. Moving costs and borrowing sit on top.
Before choosing a launch price, I would want recent comparable sales, a clear view of the current competition and a plan for reviewing the response. The first serious conversations should teach us something useful about how the home is being received.
If you are buying, use the breathing room
A softer market can give you time to compare homes, ask better questions and negotiate. It does not make every reduction a bargain.
I would look at the total commitment: the purchase price, mortgage, building costs and work you may need to do. Then ask whether the home suits your life for long enough to absorb some uncertainty.
Trying to identify the exact bottom is difficult even with hindsight. Finding a home that works, at a price you can comfortably sustain, is a decision you can examine properly today.
What will matter to you in ten years?
Imagine looking back after ten years in a home. The meals around the table, the people you had over, the children growing up, or simply the feeling of coming through your own front door. Those years have a value that a house-price chart will never capture.
I appreciate that this is only one part of a much bigger financial decision. Moving costs real money, and nobody should stretch beyond what they can comfortably manage. Sometimes waiting is exactly the right choice.
But if the finances work, the home suits you and the move would make your life better, I think that deserves real weight. There is a cost to putting your life on hold as well.
So, up or down?
On balance, I lean towards further softness in London during 2027, with some homes holding up better than the wider figures. Faster improvements in borrowing costs and confidence could change that view. Persistently expensive finance would strengthen it.
It will take realistic pricing, good preparation and careful negotiation to sell well. I would still encourage anyone who can make the move work to look at the whole picture. In ten years, the memories you made in that home may matter far more to you than whether you timed the market perfectly.
Written on 19 November 2026. Figures and forecasts were checked on that date; forecasts are the named publishers’ views, and the interpretation is mine.