Westminster’s fireworks arrive early
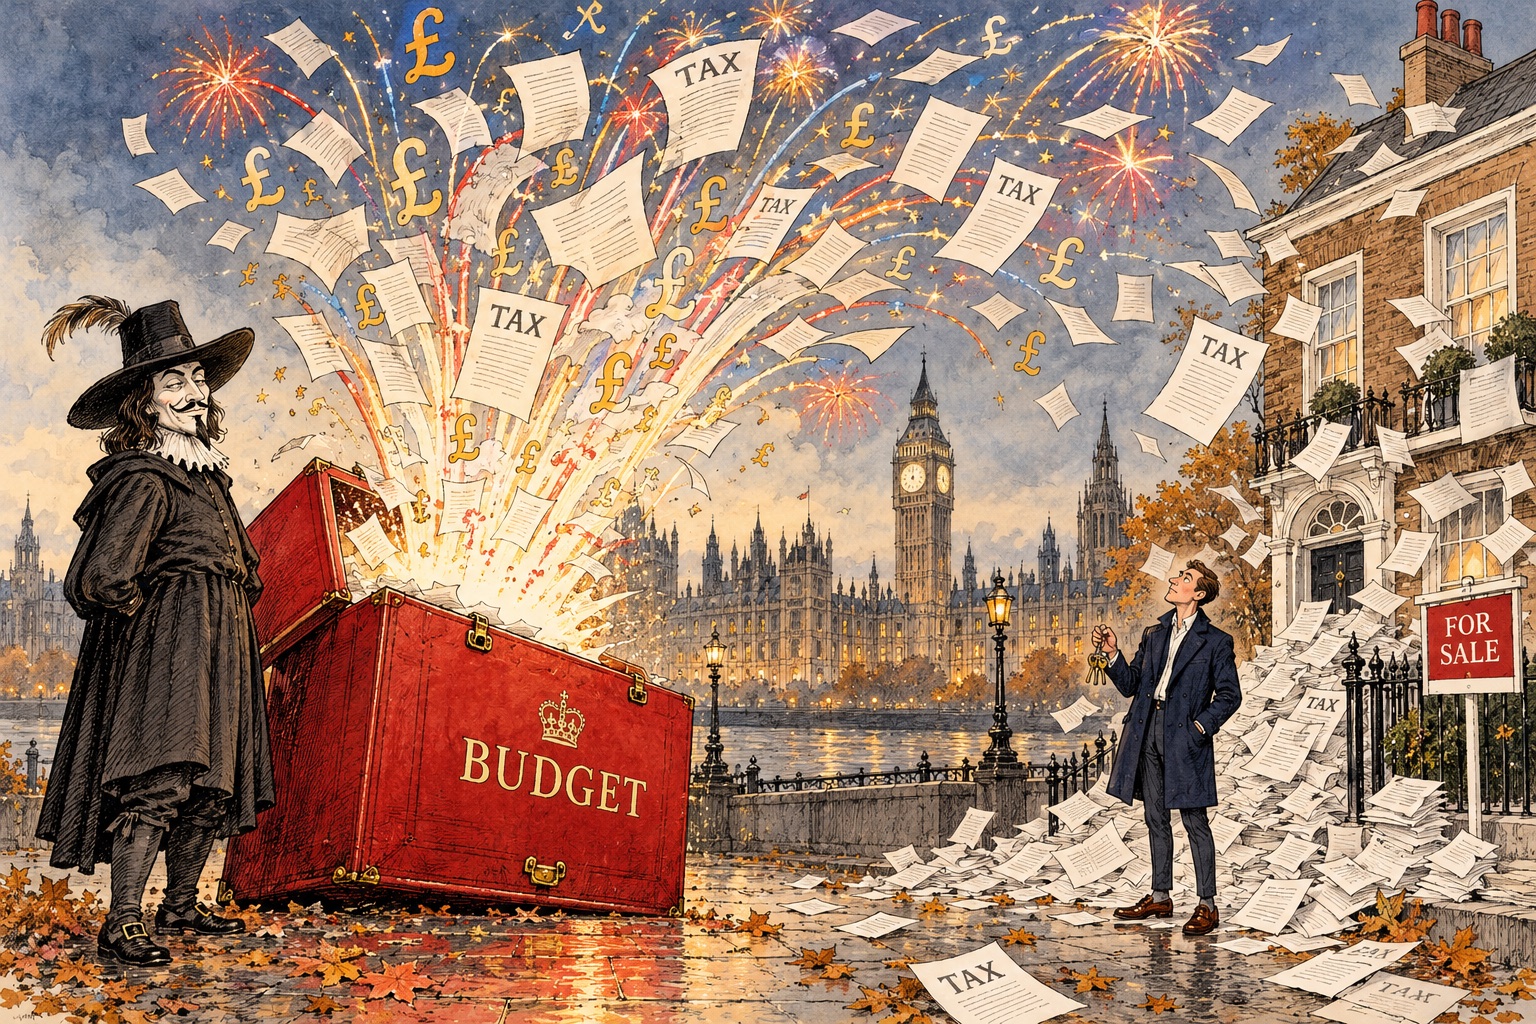
Remember, remember the fifth of November. This year, anyone trying to buy or sell a London home might want to pencil in 28 October first.
That is when the Chancellor delivers the Budget. Guy Fawkes traditionally gets one evening of national attention. The Treasury has managed to turn anticipation of its next announcement into an entire property-market season.
As someone who can become disproportionately emotional about a Georgian doorway, I appreciate a little theatre. But when people are deciding where to live, how much to borrow and whether to build a business here, a surprise ending is less appealing.
My wish for this Budget is straightforward: give people confidence to move, invest and make plans. Help first-time buyers meaningfully. Make good rental homes worth providing. And give wealth creators a reason to see their future in Britain.
There is room for tax reform and targeted reductions within that ambition. The test should be whether the whole package encourages productive activity and can be credibly funded.
A challenging market, with misleading headlines
Today’s Rightmove October report illustrates why the market can feel weaker than a headline suggests. New asking prices across Great Britain rose 1% this month but were 0.1% below a year earlier. London rose 2.5% in the month, yet remained 1.7% down annually.
In the capital, 38% of listings were being reduced and the average time to find a buyer was 78 days. Those are asking-price and marketing measures, not a completed-sale valuation of every London home.
The apparent contradiction is perfectly possible. New sellers can arrive with higher expectations while existing sellers cut theirs. Meanwhile, a buyer with a smaller borrowing budget has to make the arithmetic work, whatever the latest headline says.
The useful question is whether a particular home is attracting qualified demand at its price. Neither a national average nor a Budget rumour can answer that on its own.
From the Strait of Hormuz to a London mortgage
The backdrop extends well beyond Westminster. Conflict involving Iran, disruption around the Strait of Hormuz and uncertainty over energy supplies have consequences for household costs here. Donald Trump’s decisions on sanctions and diplomacy add another moving part: Reuters reported today that oil prices were responding to US policy changes as shipping risks continued.
The Bank of England’s September minutes held Bank Rate at 3.75%, while describing higher energy prices and tighter financial conditions. Its next decision is on 5 November. The seasonal metaphor is doing rather well.
A fixed mortgage is not simply Bank Rate plus a small margin. Lenders price funding, expected future rates and risk. The Bank recorded rapid transmission from higher market interest rates into borrowing costs, despite leaving its own rate unchanged.
Government bonds matter too. Investors assess inflation, borrowing and the credibility of fiscal plans. A Budget that unsettles those expectations can work against the cheaper finance households need.
That is why stimulus must be credible. An appealing tax cut loses some of its benefit if the wider package pushes borrowing costs higher.
First-time buyers need a workable route in
The government’s Your First Home announcement sets out a proposed route for first-time buyers in England purchasing eligible new builds: deposits expected to start at 2.5%, supported by a 20% government-backed equity loan. Income limits, local price caps and further implementation details are due at the Budget.
I understand the intention. The deposit barrier is real, particularly for people without family money. But I am sceptical of treating an equity loan as a complete affordability solution.
We need to see what happens after the initial interest-free period, how repayment works, what buyers pay for the property and how much additional housing is actually delivered. If extra purchasing power mostly supports higher prices, the advantage to the buyer is weakened. The scheme deserves to be judged on those mechanics.
It also leaves a question for buyers of existing homes, who are part of the chains that keep London moving.
Under current stamp-duty rules, eligible first-time buyers pay nothing on the first £300,000 and 5% on the portion up to £500,000. Above £500,000, that relief disappears altogether.
I would like a properly costed review of that cliff edge and the thresholds, alongside measures that expand supply. A household should be able to understand its route into ownership without relying on a parental gift or the launch date of the next scheme.
Stop making movement so expensive
Stamp duty affects more than the first rung. It changes whether families trade up, older owners downsize and people move closer to work or relatives.
A £1 million purchase at ordinary residential rates currently attracts £43,750 of SDLT, before legal fees, removals and other costs. That calculation assumes the standard rates without an additional-property or non-resident surcharge.
It is a substantial amount to spend simply on changing address. Movement can create work for builders, surveyors, removal firms and local businesses, as well as helping households use homes that fit their needs.
My preference is a sustained, costed reduction in the friction of moving, with clear transition arrangements. Temporary holidays can create a frantic deadline followed by a lull. A durable settlement would give people a better basis for planning.
There is even a Westminster case study in the system’s complexity. Angela Rayner acknowledged underpaying SDLT in 2025; the independent adviser’s report accepted that she believed the lower rate applied in good faith, while finding a breach of the Ministerial Code over her handling of the matter. She returned as Housing Secretary in July.
For once, housing policy supplied its own practical demonstration. Perhaps simpler rules could make everyone’s next move less eventful.
Prime Central London: give people a reason to stay
I want successful people to choose London. I want founders to establish businesses here, international families to put down roots and investors to back activity that creates jobs.
That is an economic preference, and it should be discussed plainly. We should also be clear about the limits of the argument: purchasing an expensive house does not automatically create a productive business, and wealthy residents still need to contribute to public services.
The question is how to sustain that contribution over time. Mobile people compare the whole proposition: taxes, schools, safety, connectivity, professional networks and confidence in the rules. London has considerable strengths. We should work to keep them.
The so-called mansion tax is already more than a rumour. The announced High Value Council Tax Surcharge is planned from April 2028 for homes in England worth £2 million or more in 2026, with published annual bands of £2,500 to £7,500. That timetable must be distinguished from speculation about further changes.
My concern is the cumulative cost and the possibility of repeated revisions. In parts of London, the word “mansion” can be doing rather more work than the floorplan.
I would like the government to assess property and residency taxation together, explain the long-term settlement and consider where reductions would improve competitiveness. We should measure success in sustained investment and economic activity, as well as the next tax receipt.
Prime Central London cannot be insulated from every global shock. But policy can make Britain easier to commit to.
Rental policy must work for tenants and good landlords
Renters need safe homes, fair treatment and a realistic choice of properties. Delivering that requires landlords who can maintain homes and make the numbers work.
Private landlords face financing, maintenance, insurance and compliance costs. For many individual landlords, the announced property-income tax changes will add another pressure: HMRC’s published policy sets separate rates of 22%, 42% and 47% from April 2027 in England, Wales and Northern Ireland.
It would be wrong to say every landlord is losing money, or that every tax increase passes straight through into rent. Outcomes depend on debt, costs, demand and the local market. But policy should test whether the combined burden discourages people from supplying decent rental homes.
Institutional investment can add useful capacity. It should complement a healthy private-landlord sector. I see little sense in celebrating housing investment when it arrives through a large fund while treating a responsible individual provider as an inconvenience.
If a rented property is sold to another landlord, its tenure may stay the same. If it becomes owner-occupied, it remains a home but leaves the rental pool. The consequences for tenants depend on what happens across the market, including whether new supply replaces it.
I want clear standards, effective enforcement against poor practice and a viable route for good landlords to remain and improve their properties.
What I want the Chancellor to deliver
My frustration with Labour’s approach is the recurring impression that property is first a source of revenue, with the question of how to encourage activity considered afterwards. The Budget is an opportunity to change that impression with a coherent programme.
Here is what I would like to see:
- A clear multi-year direction for property taxation, with fewer rolling surprises.
- First-time-buyer support judged by lasting affordability, additional supply and access to existing homes.
- A costed plan to reduce the transaction-tax burden and make moving easier.
- A competitive, predictable proposition for entrepreneurs, investors and internationally mobile families.
- A rental strategy that protects tenants while keeping responsible private and institutional investment viable.
I do not want another announcement that leaves the market waiting for the next announcement. Nor would I welcome unfunded promises that risk adding to the mortgage bill.
Broader reform requires political courage. Looking at transaction taxes, recurring property taxes, housing supply and local-government funding together is difficult. Repeatedly adding another charge is easier. I would like a government willing to do the difficult work.
My rather unfashionable wish for a boring Budget
Buyers and sellers still need to make decisions around their own circumstances. A Budget cannot correct an unrealistic asking price, remove every financing constraint or guarantee that waiting will produce a better outcome.
But government can make the rules more understandable, the costs more proportionate and the future easier to plan for.
Mark’s view: London needs a Budget that gives people the confidence to move, the means to buy and a reason to invest here.
I shall remain deeply unreasonable about replacement windows. On economic policy, I am asking for something considerably more restrained: stability, reform and enough encouragement to get on with life.
Westminster can leave the fireworks to November.